Author name: sreegesh@insightdrive.xyz

Loan & Credit

Loan Eligibility Calculator

Loan Eligibility Calculator The Loan Eligibility Calculator estimates the maximum loan amount a borrower can be sanctioned, based on their net monthly income, existing EMI obligations, and the proposed loan’s interest rate and tenure. Indian banks typically apply a Fixed Obligation to Income Ratio (FOIR) of 40–55%. This is a pre-qualification tool — it sets realistic expectations before a user applies. Results should be shown as an indicative range, not a guarantee. Gross Monthly Income ₹ ₹5K ₹5L Other Monthly Income ₹ ₹0 ₹5L Existing EMI Obligations ₹ ₹0 ₹5L Desired Loan Tenure Y 1 Y 30 Y Interest Rate (p.a.) % 5% 25% FOIR Assumption % 40% 55% Eligible Loan ₹0 Maximum EMI ₹0 Total Monthly Income ₹0 Maximum Allowable EMI ₹0 Existing EMI ₹0 Eligible EMI Capacity ₹0 Maximum Eligible Loan ₹0 Total Interest Payable ₹0 Total Repayment ₹0
Loan & Credit

Standard EMI Calculators

Standard EMI Calculators The Standard EMI (Equated Monthly Instalment) Calculator computes the fixed monthly payment a borrower must make to fully repay a loan — principal plus interest — over a chosen tenure. It is applicable to home loans, personal loans, car loans, and any amortising loan with a fixed interest rate.This is the most-used financial calculator in India. It must be pixel-perfect in accuracy because users will cross-check against bank sanction letters. Principal Loan Amount ₹ ₹1 L₹10 Cr Annual Interest Rate % 1%25% Loan Tenure Y 1 Y30 Y Monthly EMI : ₹0 Total Amount Payable ₹0 Principal Amount ₹0 Interest Amount ₹0 Monthly EMI₹0 Total Interest Payable₹0 Total Amount Payable₹0 Interest as % of Principal0% Approx. Payoff Duration0 years

ECONOMY

Cryptos and their Regulation in India

Cryptos and their Regulation in India The central authority has categorized cryptocurrency as a Virtual Digital Asset (VDA), systematically locking speculative tokens into a highly restrictive tax purgatory. By treating crypto transactions under a unique regulatory framework, the sovereign house has established an environment where traditional net-profit accounting rules completely disappear.  Before you trade highly volatile digital narratives expecting exponential portfolio expansion, you need to ask a much harder question: “Have I mathematically priced in the asymmetric tax friction designed to penalize my capital?” Navigating the heavily guarded crypto trading arena requires analysing three severe statutory barriers: Don’t chase a volatile speculative mirage while ignoring your long-term wealth foundations; trading high-frequency crypto instruments without exponential gains ensures the structural tax drag slowly drains your capital.  Watch this video to expose the asymmetric math of VDA regulations and learn how to benchmark speculative plays accurately against low-cost, tax-efficient equity index models.

ECONOMY

What The Digital Rupee Means For You

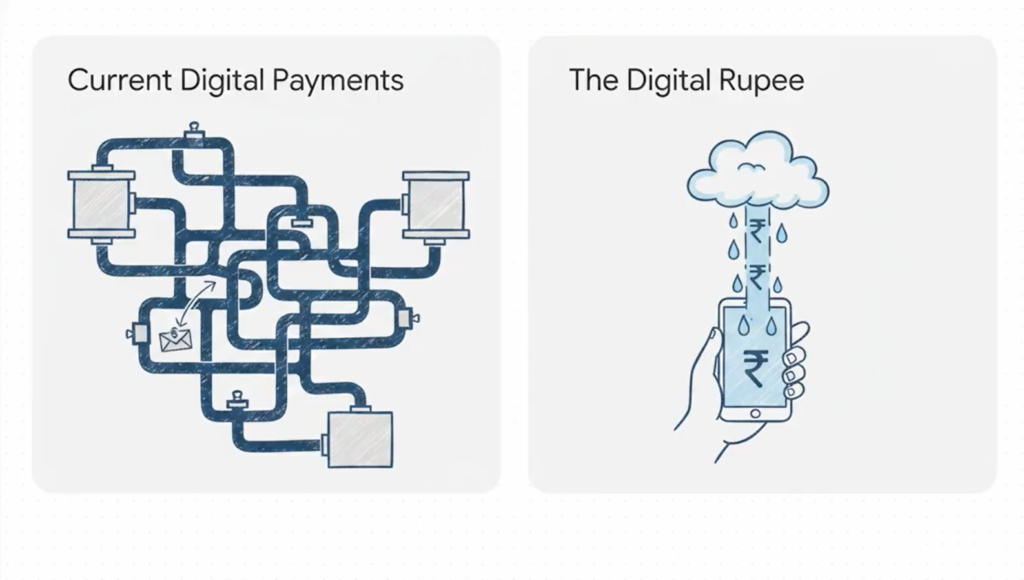
What The Digital Rupee Means For You The transformation of currency has reached its final frontier with the Central Bank Digital Currency (CBDC), converting standard money into pure digital cash backed by the sovereign credit of the state. Operating as an absolute liability of the RBI, the e-Rupee completely eliminates the commercial credit risk inherent in traditional bank deposits.  Before you confuse this sovereign token with standard smartphone applications, you need to ask a much harder question: “Do I understand the profound structural difference between the asset itself and the payment messenger?” Mastering the new digital legal tender requires tracking three high-utility structural shifts: Don’t allow excess transaction capital to accumulate idly inside your digital wallet; holding non-interest-bearing cash tokens long-term ensures your real-world purchasing power is quietly eroded by inflation.  Watch this video to unlock the full potential of programmable e-Rupees and discover how to safely balance your liquid cash tokens against your active growth assets. 

ECONOMY

AI in Financial Services: How Algorithms Decide Your Loan Approval

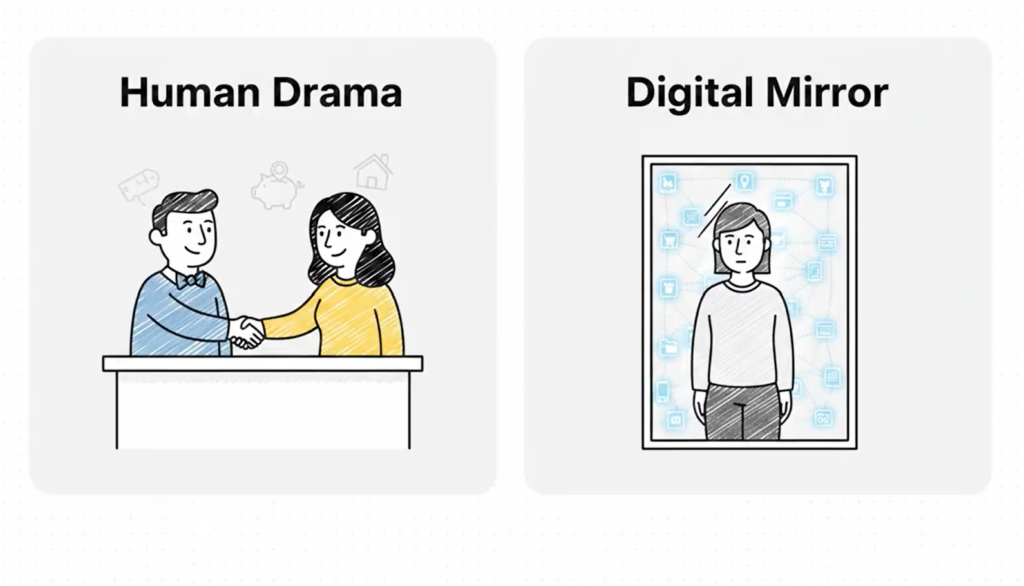
AI in Financial Services: How Algorithms Decide Your Loan Approval The traditional human drama of presenting your character to a bank manager for a loan has been permanently replaced by a ruthless digital mirror. Modern financial institutions deploy advanced machine learning algorithms to scan thousands of alternative data points in milliseconds, scoring your precise creditworthiness via automated data classification patterns.  Before you access credit or pay-later convenience tools across consumer apps, you need to ask a much harder question: “Is my unmonitored smartphone footprint flashing a severe risk signal to underwriting neural networks?” Optimizing your behavioural profile for automated underwriting models requires practicing strict digital hygiene across three data vectors: Don’t let erratic digital habits crack your financial mirror; unstructured spending signals tell the machine that your household lifestyle is completely untethered from stable earnings.  Watch this video to execute a thorough data hygiene audit on your linked bank accounts

ECONOMY

Data as Currency

Data as Currency Every swipe, tap, and digital scan you execute emits a high-resolution financial signal that institutional systems harvest, package, and utilize as a valuable shadow balance sheet. This data exhaust maps your granular behavioural heartbeat, transforming your financial reputation into a highly liquid digital currency that lenders track in real-time.  Before you routinely click “I Agree” to accelerate a digital interface, you need to ask a much harder question: “Am I trading away an invaluable long-term data asset just to capture a temporary nominal convenience?” Securing your digital vault from predatory institutional mining requires navigating three major data-sharing channels: Don’t allow unmonitored tracking permissions to clutter your risk score; unmanaged data exposure enables automated underwriting models to penalize your borrowing options.  Watch this video to build a robust digital moat around your wealth accounts and learn how to audit your active aggregator consents to preserve your financial privacy. 

ECONOMY

The Marriage Market Economy

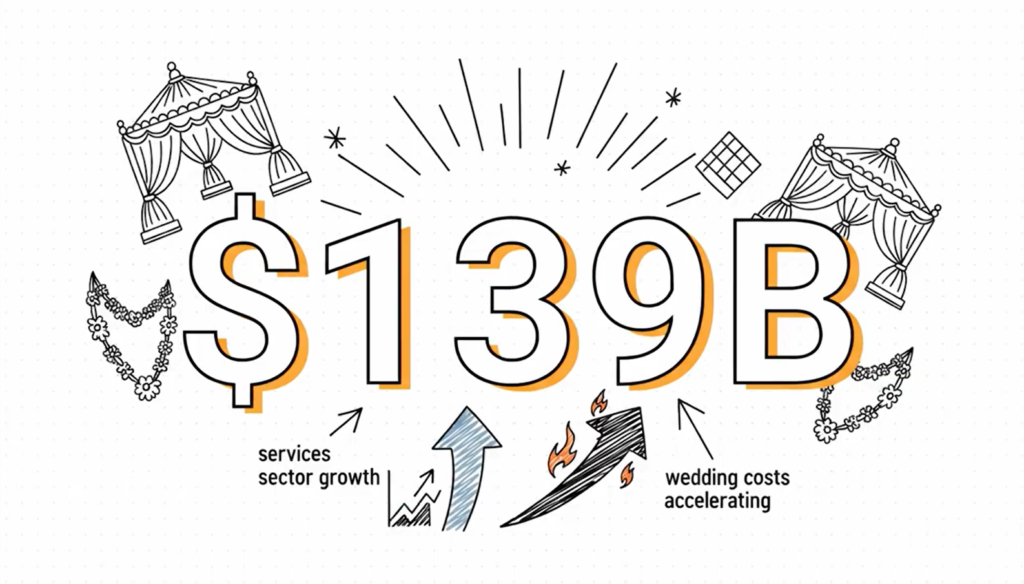
The Marriage Market Economy India’s wedding industry has ballooned into a massive $139 billion behemoth, expanding at an aggressive annual velocity of 15% that aggressively outpaces general salary increments. In this high-stakes ecosystem, weddings function as ultra-competitive positional goods where families routinely engage in heavy theatrical consumption for social signalling.  Before you greenlight a massive production budget for a single celebratory evening, you need to ask a much harder question: “Am I trading away my long-term wealth tier growth to fund a temporary nominal memory?” Scripting a sustainable wedding budget without destroying your financial health requires tackling three distinct cost traps: Don’t let competitive social indexing pressure you into over-leveraging your private silo; starting a relationship under a severe interest drag deletes your immediate career optionality.  Watch this video to implement a disciplined wedding sinking fund using the future value calculation and learn exactly how to execute a strategic guest list audit to maximize your real financial margin. 

ECONOMY

Financial Implications of Nuclear Families

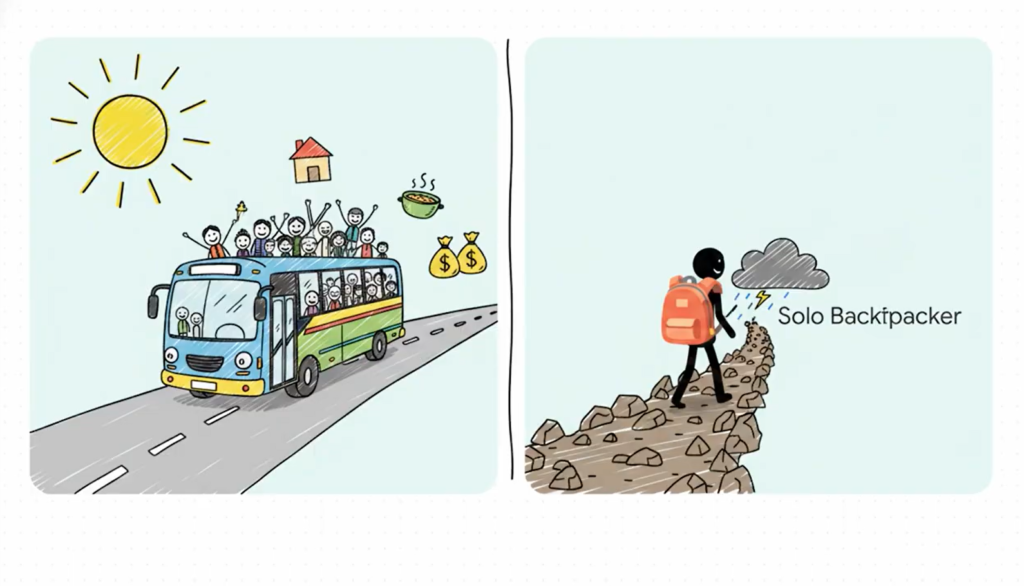
Financial Implications of Nuclear Families The structural fragmentation of the traditional Indian joint family into isolated nuclear units is fundamentally shifting the country’s risk and resource dynamics. Moving away from a shared economic caravan to operate as solo backpackers grants immense personal autonomy but permanently deletes the protective economies of scale that historically safeguarded household wealth.  Before you celebrate the lifestyle upgrades of a private household, you need to ask a much harder question: “Am I financially equipped to absorb the total loss of my family’s informal safety net?” Navigating a solo financial expedition securely requires managing three severe structural surcharges: Letting low EMIs lure you into high fixed liabilities destroys options, converting minor short-term cash flow crunches into catastrophic household crises.  Watch this video to calculate the real cost of household autonomy and discover how to deploy equity alpha to reliably self-fund your solo financial journey using the fundamental compounding formula:

ECONOMY

India’s Ageing Population

India’s Ageing Population While the mainstream economic discourse celebrates a young workforce, a silent demographic debt is accruing as India approaches an irreversible grey tsunami. With the old-age dependency ratio projected to double by 2050, traditional community safety nets are vanishing, leaving individuals entirely responsible for stocking their own retirement silos.  Before you assume your current long-term savings are sufficient to survive the winter, you need to ask a much harder question: “Am I relying on a fragile nominal fallback or a real compounding engine?” Stocking your private retirement silo before the growing season ends requires balancing two contrasting financial gears: Treating children as retirement assets or resting on stagnant family properties destroys options, transforming a thirty-year retirement winter into a catastrophic cash crunch.  Watch this video to calculate the true future cost of your lifestyle and discover how to deploy disciplined equity exposure to secure your financial independence. 

ECONOMY

Urbanisation and its Financial Implications

Urbanisation and its Financial Implications The massive demographic migration shifting India’s population toward urban hubs operates as a powerful economic magnet, completely rewriting how wealth is generated, stored, and spent. By 2030, an estimated 600 million people will reside in Indian cities, driving a rapid structural transition away from volatile, seasonal agricultural earnings toward high-velocity urban output.  Before you allocate your real estate capital into stagnant legacy markets, you need to ask a much harder question: “Am I tracking the infrastructure multipliers that dictate the real value of emerging cities?” Riding the tidal wave of national urban migration requires mapping out three critical economic transformations: Don’t let lifestyle inflation erode your urban earnings; your career alpha and asset selection must actively keep pace with the sheer velocity of population density.  Watch this video to decode the forward-looking map of Indian urbanization and learn exactly how to identify satellite property zones built for exponential growth.

Book an Appointment Form