Author name: sreegesh@insightdrive.xyz

ECONOMY

Personal Inflation

 Personal Inflation: Escaping the “Average Trap” When official data shows consumer price indexes sitting comfortably at 3.4%, but your actual monthly outlays have surged by a painful 10%, you aren’t imagining things. The national CPI is a broad-brush tool designed to measure the basic survival baseline of 1.4 billion people, heavily skewing it away from a modern lifestyle.  Before you blindly trust standard online retirement calculators to plan your long-term independence, you need to ask a much harder question: “What is my true Personal Inflation Rate?”  Escaping the statistical average trap requires auditing three brutal lifestyle premiums that national metrics ignore: Relying on generic national inflation data will leave your emergency funds and retirement corpus dangerously underfunded over time; you manage a personal economy, not a national average.  Watch this video to calculate your exact Personal Inflation Rate and learn how to construct an investment strategy that outpaces your real-world cost of living. 
ECONOMY

Open Market Operations

Open Market Operations Many investors treat debt mutual funds as completely safe, fixed-return havens, only to face a sudden shock when their portfolio’s NAV drops unexpectedly. The hidden driver behind these sudden market movements is often Open Market Operations (OMOs)—the RBI’s absolute favourite tool for controlling countrywide cash flow.  To protect your debt portfolio from unexpected hits, you must understand how the central bank adjusts the volume of the bond market.  The RBI’s open market bond trading alters your investment returns through three distinct mechanics: Open Market Operations are the RBI’s volume control; failing to match your debt fund’s duration to your actual investment horizon transforms a safe asset into an unmanaged interest rate bet.  Watch this video to decode how the RBI’s current OMO strategy impacts bond yields in 2026, and learn exactly which debt funds fit your financial timeline. 

ECONOMY

 Forex Reserves: The Nation’s Silent Bodyguard

 Forex Reserves: The Nation’s Silent Bodyguard Just as a smart household maintains an emergency fund to cover unexpected shocks, a country builds a multi-billion-dollar war chest to insure itself against global financial accidents. Clocking in at a robust $697.12 billion in April 2026, India’s foreign exchange reserves serve as the ultimate defence mechanism for your standard of living.  Instead of viewing these massive reserves as idle cash, you must recognize them as an active shield protecting your daily purchasing power.  This national insurance policy protects your personal finances through three critical components: A sudden drop in headline forex reserves isn’t a sign of national failure; it means your financial bodyguard is actively absorbing a global shockwave so your household budget doesn’t have to.  Watch this video to understand the anatomy of India’s 2026 war chest and learn how central bank gold accumulation signals long-term shifts in the global economy.

ECONOMY

Currency Markets: The RBI’s Invisible Shield

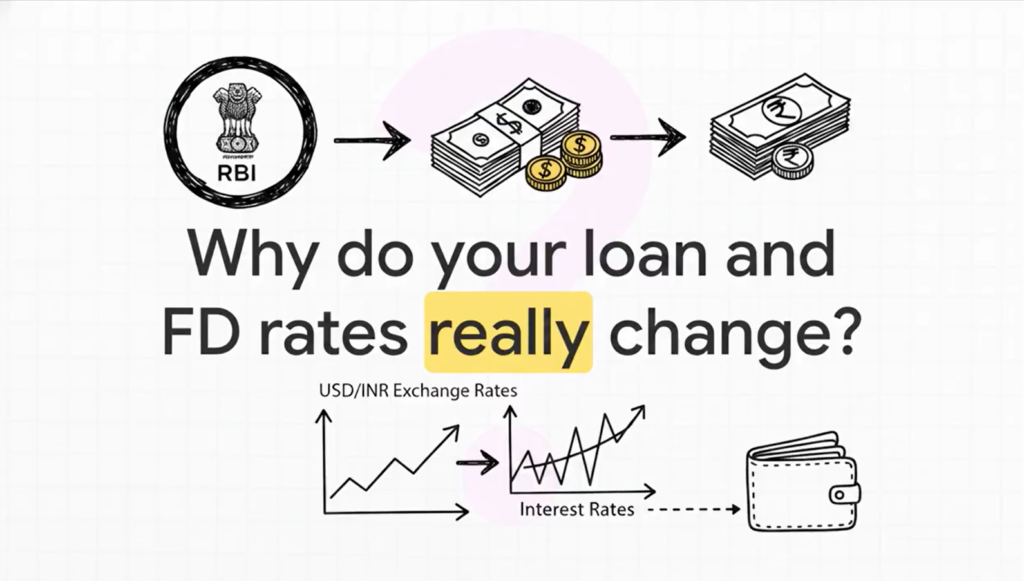
Currency Markets: The RBI’s Invisible Shield Most people think the RBI’s currency interventions are just about maintaining a specific nominal target for the Indian Rupee against the US Dollar. In reality, the central bank cares purely about managing wild volatility—and their massive institutional trades directly dictate what you pay for retail loans or earn on your savings.  Understanding how the RBI defends the currency is the secret to predicting domestic credit conditions before they hit your personal wallet.  The central bank’s currency market operations trigger a powerful chain reaction across the domestic banking system: Your home loan interest rate isn’t just about local factors; if global currency shifts force the RBI to defend the rupee, expect tighter domestic credit conditions to follow within weeks.  Watch this video to discover how the RBI’s dollar trades impact your everyday finances and learn to read currency headlines like an institutional investor.

ECONOMY

Reverse Repo, SDF, MSF

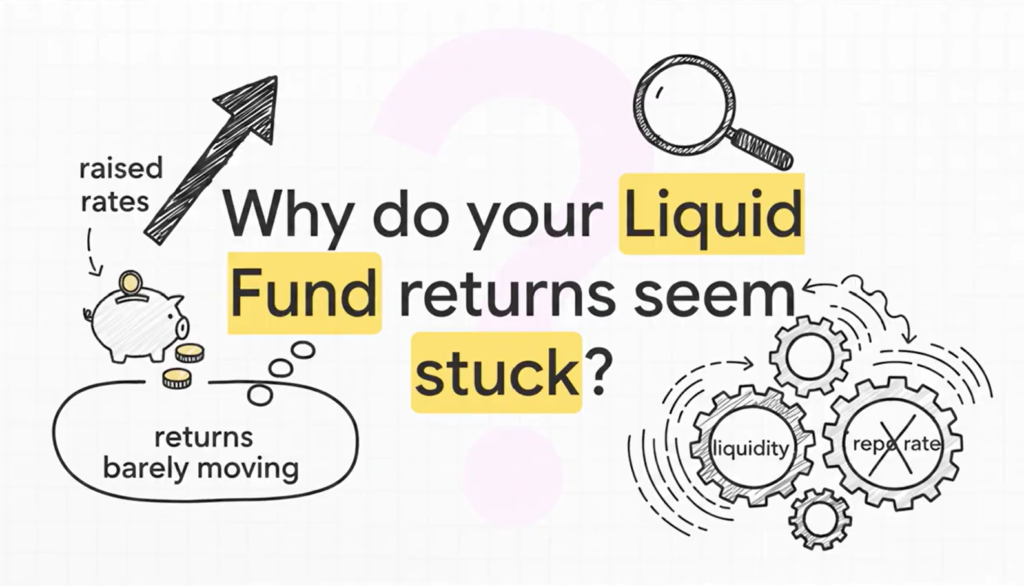
Reverse Repo, SDF, MSF While the headline repo rate captures all the mainstream media attention, the true return on your short-term cash is actually governed by a hidden 50-basis-point corridor. Run by the RBI, this system dictates why your “safe” liquid mutual funds can feel stuck even when headline interest rates look highly attractive.  To unlock better returns on your idle cash, you must look past the anchor rate and understand the boundaries of the Liquidity Adjustment Facility.  The returns on your short-term debt investments trade within the space of three institutional pillars: Your liquid mutual fund is not a fixed-return product; failing to monitor systemic liquidity shifts means settling for basement yields when you could be capturing short-term return spikes.  Watch this video to map out the 2026 liquidity corridor and learn exactly how to manage your short-term cash between liquid and overnight buckets. 

ECONOMY

Interest Rate Cycles

Interest Rate Cycles Interest rates act like a massive macroeconomic pendulum, swinging predictably between inflation-cooling upswings and growth-focused downswings. In early 2026, the Indian market transitioned away from a high-interest regime of 6.5%, entering a stable, 5.25% neutral pause phase.  Instead of trying to guess the absolute bottom or top of the market, you must learn to position your assets according to the current cyclical season.  Maximizing your wealth through this interest rate cycle requires understanding three core strategic pivots: Never attempt to perfectly time the macroeconomic pendulum; executing your wealth strategy in disciplined tranches ensures you win no matter which way the cycle swings next.  Watch this video to learn the exact playbook for balancing fixed deposits, mutual funds, and loan prepayments during this 2026 interest rate pause. 

ECONOMY

Purchasing Power Parity

Purchasing Power Parity Looking at a market ticker shows the US Dollar trading at roughly ₹93 in April 2026, making the Indian currency look weak on the global stage. However, that nominal exchange rate completely misses the “Lifestyle Rate”—what that money actually buys you in a Mumbai market versus a New York deli.  To understand the real size of your global wealth, you must stop looking through the lens of nominal airport exchange rates and look at Purchasing Power Parity (PPP).  The gap between what a currency is worth on the stock ticker and its real local strength is defined by three factors: Don’t be blinded by foreign currency multipliers; a high-nominal foreign salary often buys a lower-quality lifestyle than strategic rupee deployment inside India’s internal economy.  Watch this video to learn how to arbitrage the PPP gap as an investor, freelancer, or career professional in 2026. 

ECONOMY

The Business Cycle

The Business Cycle The economy never moves in a straight line; it breathes in a recurring, wave-like rhythm of ups and downs known as the Business Cycle. While the Western world panics over potential recession fears in 2026, India is pulling off a historic “soft landing”—successfully cooling inflation down to 3.4% while sustaining robust 7.8% economic growth.  Understanding exactly where we sit in this economic rhythm is the ultimate line between executing a brilliant investment and making a catastrophic financial mistake.  Navigating these economic seasons requires mastering the levers that control the market’s heartbeat: You cannot stop the economic seasons from changing, but you can change your clothes; adjusting your career moves, debt structures, and asset choices ensures you remain protected in any climate.  Watch this video to master the 2026 financial playbook and align your career trajectory, fixed deposits, and SIPs to the current heartbeat of the market.

ECONOMY

Inflation: The Basics

Inflation: The Basics When prices crawl upward across the country, it doesn’t just mean your weekly expenses are rising; it means the purchasing power of your money is being systematically stripped away. A stable 3.40% Consumer Price Index (CPI) in early 2026 sounds harmless on paper, but your hard-earned cash is silently losing its muscle while sitting idle.  Instead of asking how you can cut back to save cash, you need to ask a more critical question: “How do I make my wealth grow faster than the true cost of living?”  Inflation acts as a hidden tax on your lifestyle, functioning through three specific wealth-destroying mechanisms: Standing still with your cash in April 2026 is the riskiest financial move you can make; inflation is the gravity of the financial world, and you must out-invest it simply to stay at the same height.  Watch this video to calculate your personal CPI and discover how to deploy equities, gold, and strategic debt to permanently neutralize the invisible thief.

Financial Frauds & Safety

Be Sure It’s Your Bank

Be Sure It’s Your Bank 1. Is It Really My Bank Calling? You receive a call at an odd hour and the person speaking at the other claims that they are calling you from your bank.  How can you be sure that it’s your bank that’s calling and not a fraudster? By looking at the 10-digit incoming call number. Banks in India are mandated to use specific number series when calling customers/prospects. Calls from these numbers help distinguish genuine bank communications from scams. 2. Is It Really My Bank’s Website? You receive a WhatsApp message from what looks like your bank that is asking you to click on a link and update your personal information.  Firstly, DO NOT CLICK on any links received on any of the social media platforms.  Secondly, how do you ensure that it’s your bank’s genuine Website that you are accessing? Look for the domain ending in “.bank.in” Whether you have an account with a private bank like HDFC or a public sector bank like SBI or a foreign bank like HSBC or a small regional rural bank (RRB) or a cooperative bank, all their Websites in India will now have a unique domain that ends with .bank.in, which isn’t available for anyone else to register.  3. Is it Really My Insurance Company’s Website? Like with banks, RBI has introduced the .fin.in domain for all Non-Banking Finance Companies (NBFCs) including insurance companies.  These changes mandated by RBI  will significantly enhance cybersecurity and trust in India’s financial ecosystem. These changes will help curb digital fraud, protect consumers, and establish a secure online presence for financial institutions. Unlike regular “.com” or “.in” domains, “.bank.in” or “.fin.in” are exclusive to verified Indian banks, ensuring that customers can easily identify authentic websites. 

Book an Appointment Form