Author name: sreegesh@insightdrive.xyz

Insurance

Health Insurance Claim Rejections

Health Insurance Claim Rejections This guide breaks down the seven most common reasons for health insurance claim rejections, such as non-disclosure of medical history, active waiting periods, and documentation gaps. It reassures policyholders that many rejections are reversible if the underlying pattern is properly identified and addressed promptly. For each rejection type, the text provides actionable steps for resolution, ranging from retrieving missing hospital documents to challenging broad policy exclusions. It concludes with a structured process for handling any denial, including escalating the issue to the Insurance Ombudsman when necessary.

Insurance

The Policyholder Rights Lens

The Policyholder Rights Lens This file shifts the focus from simply owning a health insurance policy to actively enforcing a policyholder’s legal rights under the new IRDAI guidelines. It details ten fundamental entitlements, including the ability to demand cashless treatment at any hospital and strict timelines for claim settlements and hospital discharges. The text emphasizes the importance of the reduced five-year moratorium shield, which protects long-term policyholders from late-stage claim disputes. By internalizing these rights, consumers can effectively advocate for themselves and challenge unfair practices by insurance companies.

Insurance

IRDAI’s Health Insurance Updates

IRDAI’s Health Insurance Updates This document outlines the key updates from the Insurance Regulatory and Development Authority of India’s (IRDAI) 2024 consolidated Master Circular. It explains significant consumer-friendly changes, such as capping the pre-existing disease waiting period at 36 months and removing the maximum age limit for purchasing new policies. Additionally, it highlights the reduction of the moratorium period to five years and the extension of the free-look period to 30 days. Ultimately, this guide serves to help policyholders understand these new rules and verify their existing policies during renewal.

Questionnaires

Can You Afford This Loan ?

Can You Afford This Loan? Decision Support • Debt & Borrowing • Complete the questionnaire below 1. What is your gross monthly income? Include salary, rental income, business income and all regular sources. Monthly Income (₹) 2. What are your total existing EMIs per month? Do not include the proposed new loan. Existing EMIs (₹) 3. What is the loan amount you are considering? Loan Amount (₹) 4. What is the annual interest rate on the proposed loan? Common rates: Home 8–9.5%, Car 8–12%, Personal 11–24%. Interest Rate (%) 5. What is the proposed loan tenure? Tenure Value Unit MonthsYears 6. How many months of essential expenses do you have in liquid savings? 0 Months1–2 Months3–5 Months6–11 Months12+ Months 7. What is your income type? Salaried (Private Sector) Salaried (Government / PSU) Self-employed Professional Business Owner Other 8. What is the purpose of this loan? Home PurchaseHome RenovationCar PurchaseEducationMedical EmergencyDebt ConsolidationPersonalBusiness ExpansionConsumer Goods / Lifestyle 9. How many financial dependants do you have? 01234+ I have read and agree to the Terms & Conditions, Disclaimer and Privacy Notice Calculate Results This questionnaire is for educational purposes only and does not constitute financial advice. Standard Disclosures, Caveats and Terms of Use × Important Disclaimer This questionnaire is for financial self-education and awareness purposes only. It does not constitute financial advice, investment advice, tax advice, or any regulated financial service. tackl.finance is not a SEBI-registered Investment Adviser, IRDAI-registered insurance intermediary, or AMFI-registered distributor. The outputs generated by this tool are indicative only and are based solely on the information entered by the user. Scope and Limitations All calculations are based solely on the information provided by the user. Results are only as accurate as the inputs entered. The questionnaire uses standardised rules of thumb and widely accepted financial benchmarks. Individual circumstances may differ materially from these benchmarks. Tax calculations, where applicable, use prevailing Indian Income Tax Act provisions as understood at the time of publication. Tax laws change; users must verify current provisions with a qualified tax adviser. Interest rates, inflation assumptions, and market return assumptions used in calculations are indicative only. Actual rates and returns will differ. This tool does not access or store any bank account, investment account, credit bureau, or other personal financial data. All data is entered manually by the user. Data Privacy tackl.finance does not store, share, or sell any personal financial information entered into this questionnaire. Results are generated and displayed within the user’s browser session. If the user navigates away, results are not retained unless the user saves or prints them. Users are advised not to enter sensitive information such as account numbers, PAN numbers, or Aadhaar numbers in any free-text field. Terms of Use By using this questionnaire, the user acknowledges that tackl.finance bears no liability for any financial decision made based on the results of this tool. The questionnaire is intended for adults aged 18 years and above who are resident in India. Results are for the user’s personal use only and should not be shared as professional financial guidance with third parties. tackl.finance reserves the right to update, modify, or withdraw any questionnaire without prior notice. Recommended Next Steps Consult a SEBI-registered Investment Adviser for investment-related decisions. Consult an IRDAI-registered insurance broker or adviser for insurance decisions. Consult a Certified Financial Planner accredited by FPSB India for comprehensive financial planning. Consult a practising Chartered Accountant for tax-related decisions. 1. Overview and Purpose This questionnaire helps the user evaluate whether taking on a new loan is financially prudent given their current income, existing obligations, emergency reserves, and the nature of the loan. It applies to home loans, car loans, personal loans, education loans, and business loans. The primary output is a traffic-light recommendation based on established Indian banking benchmarks. The Fixed Obligation to Income Ratio is the central metric used to assess loan affordability. The questionnaire also assesses emergency fund adequacy, income stability, loan purpose, and the number of financial dependants.
Government Schemes

Ayushman Bharat Pradhan Mantri Jan Arogya Yojana (AB PM-JAY)

Ayushman Bharat Pradhan Mantri Jan Arogya Yojana (AB PM-JAY) AB PM-JAY (launched 23 September 2018) is the world’s largest publicly funded health insurance scheme, covering approximately 12 crore families with over 42 crore Ayushman Cards issued. It provides ₹5 lakh per family per year of cashless, paperless hospitalisation cover (secondary and tertiary care, 1,929+ treatment packages) at 32,320+ empanelled hospitals across India, with full portability, pre-existing conditions covered from day one, three-day pre-hospitalisation and 15-day post-discharge cover, and no cap on family size. Eligibility for the core scheme is SECC 2011-based (six deprivation markers in rural, eleven occupational categories in urban areas). A landmark 2024 expansion — Ayushman Vay Vandana Yojana (AVVY), launched 29 October 2024 — extends PM-JAY to all Indian citizens aged 70+, regardless of income or SECC status. Existing PM-JAY families with 70+ members get an additional exclusive ₹5 lakh/year top-up for those seniors (up to ₹10 lakh household total); non-SECC seniors get an individual ₹5 lakh/year cover via Aadhaar e-KYC self-enrolment on the Ayushman App. CGHS/ECHS holders must choose between those schemes and AVVY; private insurance holders can use AVVY additionally. As of March 2026: 3.4 crore+ seniors enrolled, ₹4,200+ crore in claims authorised (primarily cataract, knee replacement, cardiac, dialysis). Key gap: OPD costs not covered.

Government Schemes

Kisan Credit Card

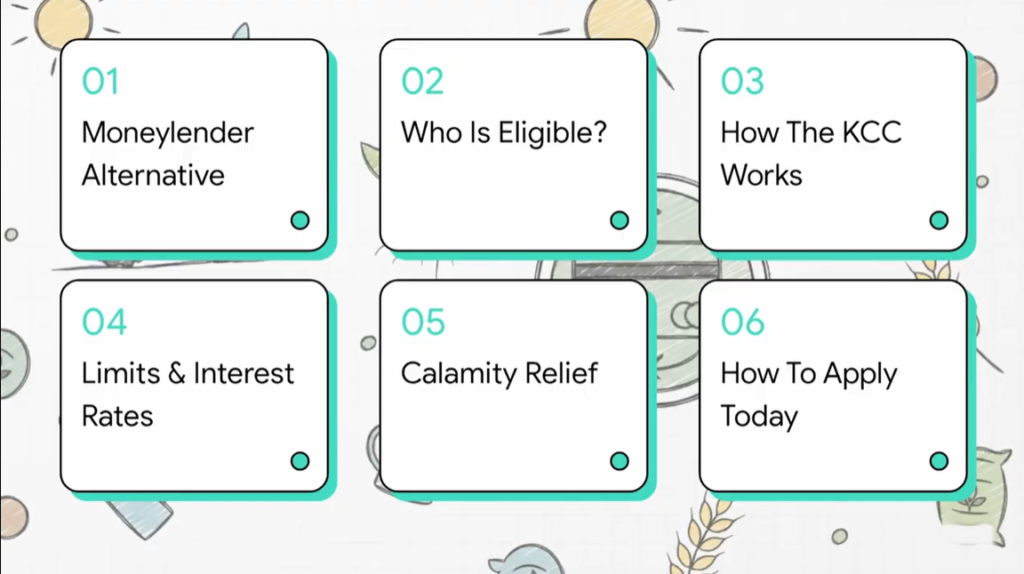
Kisan Credit Card The Kisan Credit Card (KCC), launched in 1998 by NABARD, provides revolving cash credit for short-term agricultural and allied-activity expenses at subsidised rates, through any commercial bank, RRB, Small Finance Bank, or cooperative bank. Under the Modified Interest Subvention Scheme (MISS), the government provides 1.5% interest subvention to banks, bringing the farmer’s rate to 7%; an additional 3% Prompt Repayment Incentive (PRI) for timely repayment brings the effective rate to 4% per annum. Budget 2025-26 raised the crop loan limit eligible for MISS from ₹3 lakh to ₹5 lakh, and the fisheries/animal husbandry limit from ₹2 lakh to ₹5 lakh. Effective January 2025, the collateral-free credit limit was raised from ₹1.6 lakh to ₹2 lakh per borrower. KCC operates as a 5-year revolving credit line (annually reviewed), repaid from harvest proceeds, with a RuPay debit card for ATM/POS access and PMFBY insurance bundled. For natural calamities, outstanding KCC balances can be converted to term loans with interest relief for up to 1 year (extendable to 5 years for severe disasters). Extended to fisheries and animal husbandry since 2018-19. As of 2025: approximately 7.72 crore operative KCC accounts with over ₹10 lakh crore outstanding.

Government Schemes

Affordable Rental Housing Complexes Scheme (ARHC)

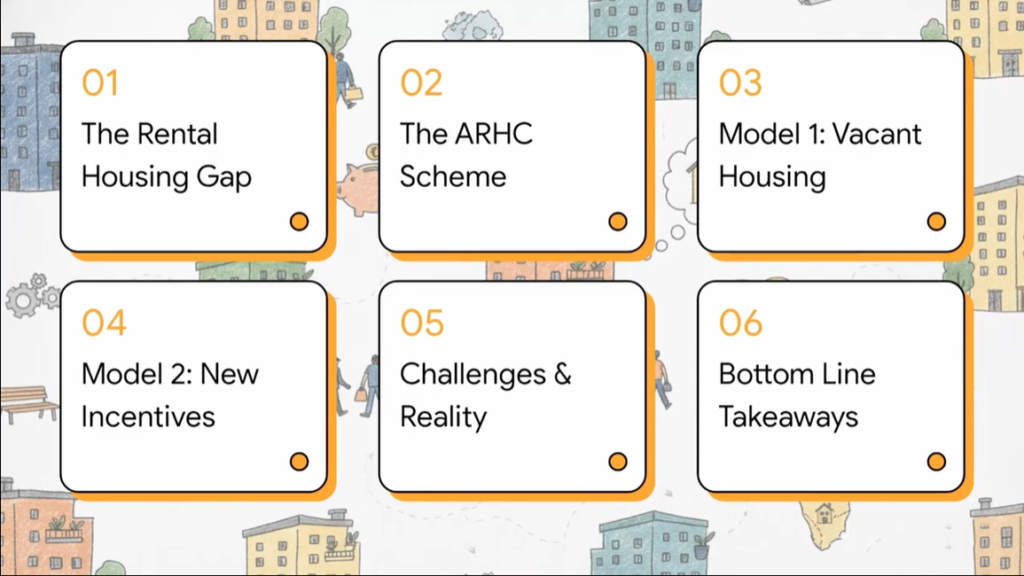
Affordable Rental Housing Complexes Scheme (ARHC) The Affordable Rental Housing Complexes (ARHC) scheme, launched in May 2020 under Atmanirbhar Bharat as a sub-scheme of PMAY-Urban, addresses the acute gap in formal rental housing for urban migrants, industrial workers, and the urban poor. Unlike most GoI housing schemes focused on ownership, ARHC explicitly targets the rental market. Two models operate: Model 1 converts existing vacant government-funded housing stock (from JNNURM/RAY/PMAY) into rental complexes via 25-year concessionaire arrangements with ULBs setting rents; Model 2 incentivises public/private entities to build new ARHC units on their own land through a Technology Innovation Grant, additional FAR/FSI, priority sector lending classification for construction loans, Section 80-IBA income tax exemptions, and GST relief. Target beneficiaries include industrial workers, students, economic zone workers, migrants, and the urban poor generally. This note provides an honest assessment: Model 1 has faced practical barriers (location, quality, legal complications in vacant stock), and Model 2 has seen limited private uptake despite incentives, making ARHC’s overall scale substantially below its 2020 ambition. Availability is geographically uneven; interested individuals and employers should check with their local ULB or state PMAY nodal agency for projects in their area.

Government Schemes

Pradhan Mantri Fasal Bima Yojana (PMFBY)

Pradhan Mantri Fasal Bima Yojana (PMFBY) PMFBY (launched 2016, replacing NAIS/MNAIS) is India’s flagship crop insurance scheme — the world’s largest by enrolments — covering all farmers (including sharecroppers and tenant farmers) growing notified crops, at capped farmer premiums of 2% (Kharif food/oilseed), 1.5% (Rabi food/oilseed), and 5% (commercial/horticultural), with the balance subsidised by Centre and states. Made voluntary for all farmers (including loanee farmers) from February 2020. Coverage spans prevented sowing, standing crop losses, post-harvest (up to 14 days), and localised calamities — with wild animal attacks and paddy inundation added as new add-on covers from Kharif 2026. Claims are area-based for standing crop (via Crop Cutting Experiments) and field-level for localised losses (72-hour reporting via app/Kisan Rakshak helpline 14447), paid via DBT. Key recent reforms: 12% per annum penalty on insurers for delayed claim payments (from Kharif 2024) and mandatory state escrow accounts for premium share deposits (from Kharif 2025) — both addressing historically poor claims timeliness. Total claims disbursed over the scheme’s life: over ₹1,72,000 crore against ₹34,500 crore in farmer premiums.

Government Schemes

Aam Aadmi Bima Yojana (AABY)

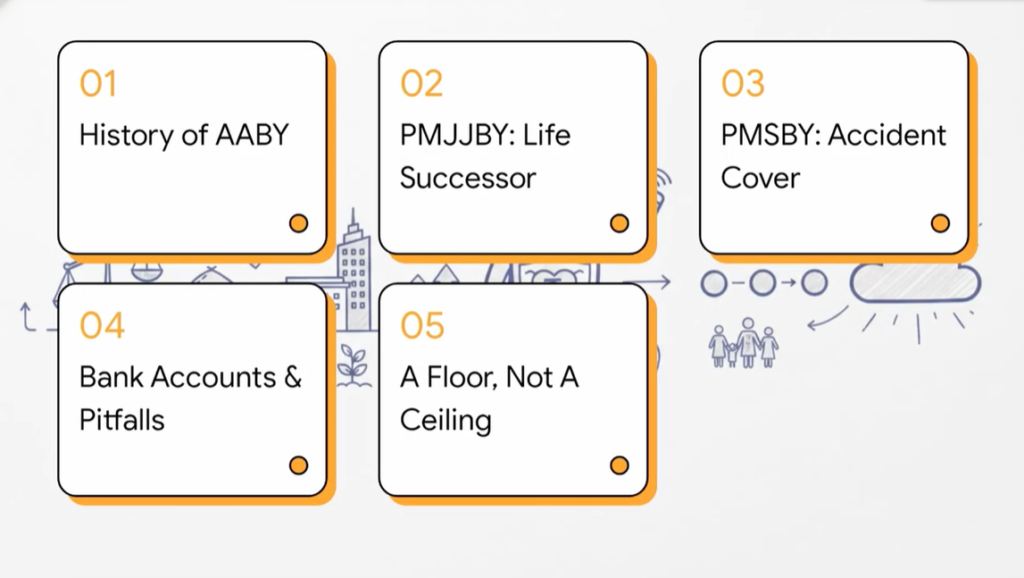
Aam Aadmi Bima Yojana (AABY) Aam Aadmi Bima Yojana (AABY), launched in 2007 for rural landless households and unorganised-sector workers (₹30,000 natural death / ₹75,000 accidental death cover at a ₹200/year subsidised premium via LIC), was merged into PMJJBY and PMSBY with effect from 1st June 2017 and is no longer open for new enrolments — this note covers that history briefly before focusing on its two successors. PMJJBY provides ₹2 lakh any-cause life cover for ages 18–50 (renewable to 55), while PMSBY provides ₹2 lakh accidental death/total disability cover (₹1 lakh for partial disability) for ages 18–70 — both operate via annual bank-account auto-debit at minimal premiums, with a common pitfall being redundant enrolment (and premium deduction) across multiple bank accounts for the same person. We note the September 2025 GST exemption on health/term insurance as relevant context, and frame PMJJBY/PMSBY as a low-cost baseline of protection that most individuals with meaningful dependents or liabilities should supplement with adequately-sized private term insurance, covered elsewhere in tackl.finance’s insurance notes.

Book an Appointment Form