Author name: sreegesh@insightdrive.xyz

Bank Accounts

Education Loans

Education Loans Education loans are shaped by the IBA’s Model Education Loan Scheme (2022), with a tiered collateral structure: no collateral or guarantor up to ₹4 lakh, a guarantor (but no collateral) up to ₹7.5 lakh, and collateral required above that — though private lenders often extend collateral-free limits well beyond ₹7.5 lakh based on institution, course, and co-applicant profile. This guide covers what’s financed (tuition, accommodation, books/equipment, and study-abroad travel), interest rates (secured vs unsecured, benchmark-linked), and the moratorium period — where simple interest accrues during the course-plus-grace-period even though EMIs are paused, with a real choice between servicing this interest or letting it capitalise into the principal. We detail two distinct government interest-subsidy schemes (CSIS for economically weaker students in India, and the Dr. Ambedkar Central Sector Scheme for OBC/EBC students covering both India and study abroad), PSL classification, the Vidya Lakshmi common application portal, and Section 80E — the uncapped interest-only tax deduction available for 8 years from the start of repayment, for loans taken for the borrower, spouse, children, or legal wards.
Bank Accounts

 Loan Against Securities

 Loan Against Securities (LAS) Loan Against Securities (LAS) lets you borrow — usually via an overdraft, with interest charged only on amounts utilised — against a lien on equity shares, mutual funds, bonds, or insurance policies, without selling them or losing dividends/interest/corporate-action benefits. This guide covers how liens are created (via NSDL/CDSL for demat holdings, via RTAs like CAMS/KFin for mutual fund units), and the central fact of LAS: LTV varies significantly by security type — equity shares are the most conservative (and subject to lender “approved lists”), equity mutual funds somewhat more generous, and debt instruments typically the most generous, mirroring the volatility concepts from tackl.finance’s markets and bonds notes. We explain margin calls in detail — what triggers them, what happens if they’re not met (forced liquidation), and why this makes LAS’s risk profile fundamentally different from property- or gold-backed loans, where collateral values move far more slowly. We close with the end-use-dependent tax treatment and guidance on when LAS is a sensible liquidity tool versus a risky leverage-on-leverage strategy.

Bank Accounts

Gold Loans

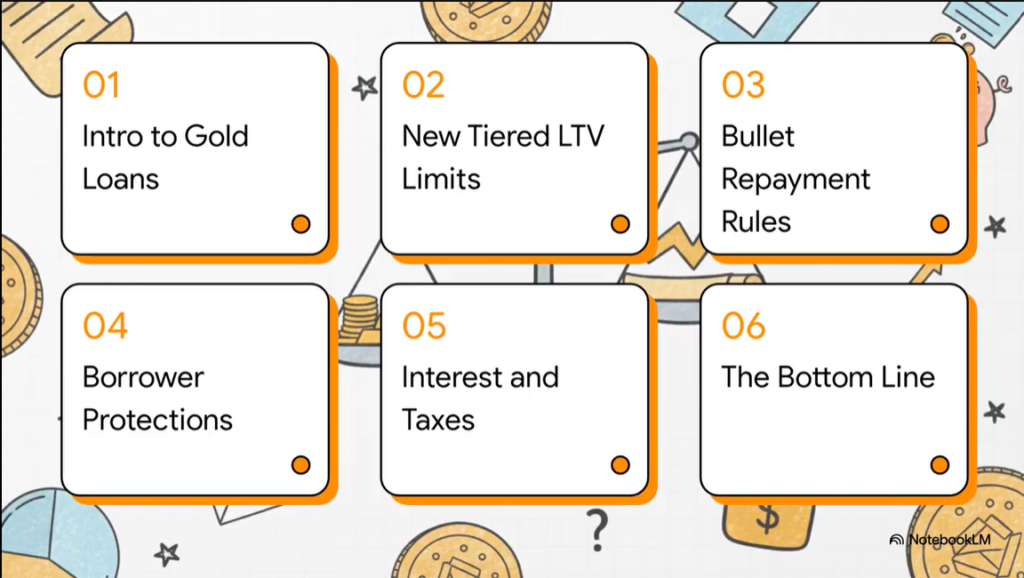
Gold Loans Gold loans — secured against pledged gold/silver jewellery, ornaments, and coins — are governed by a comprehensive new RBI framework finalised in 2025 and effective from 1 April 2026. This guide covers the headline change: LTV limits are now tiered by loan size (up to 85% for loans up to ₹2.5 lakh, 80% for ₹2.5–5 lakh, and 75% above ₹5 lakh, versus the earlier flat 75% cap), and must be maintained throughout the loan’s tenure, not just at disbursement. For bullet-repayment loans — now capped at 12 months — LTV must be calculated on the full amount repayable at maturity (principal plus accrued interest), which means the effective upfront disbursement is lower than the headline LTV percentage suggests. We also cover new borrower protections (verifiable proof of ownership, documented purity/valuation basis, a 7-working-day gold-return deadline backed by a ₹5,000/day penalty, simplified norms for loans under ₹2.5 lakh, and transparent auction requirements on default), repayment structure options, banks vs NBFCs, and the end-use-dependent tax treatment that mirrors LAP and top-up loans.

Bank Accounts

Auto Loans

Auto Loans An auto loan is secured by the vehicle itself, recorded as a “hypothecation” on the Registration Certificate — giving the lender a claim on the vehicle until full repayment, and requiring formal removal (via Form 35 and the lender’s NOC) once the loan closes. This guide covers LTV differences between new and used cars (and the correspondingly shorter tenures for used-car loans), and makes a key point often missed: most auto loans are fixed-rate, so the 2026 RBI (Pre-payment Charges on Loans) Directions — which apply to floating-rate loans — generally don’t protect auto loan borrowers from prepayment charges, unlike home loans and LAP. On tax: personal-use auto loan interest is never deductible, business-use vehicles can claim interest and depreciation under PGBP, and Section 80EEB’s EV interest deduction applied only to loans sanctioned by 31st March 2023 — it does not apply to new EV loans today. We also cover mandatory comprehensive insurance, bundled-insurance trade-offs, and car refinance as a lower-LTV alternative to top-up loans.

Bank Accounts

Top-Up Loans

Top-Up Loans A top-up loan adds borrowing on top of an existing loan — typically a home loan — from the same lender, using the same collateral and an already-established relationship, making it fast to process and typically cheaper than a personal loan. This guide covers eligibility (repayment track record, remaining LTV headroom, and combined-EMI affordability), why top-up rates run slightly above the base loan rate, and tenure alignment with the base loan. The central focus is a frequently-missed tax nuance: top-up interest is deductible under Section 24(b) only if the funds are demonstrably used for construction, repair, or improvement of a house property — not automatically, just because it’s an extension of a home loan — making documentation of end-use essential. We also cover how the new 2026 RBI prepayment-charge rules apply to top-ups specifically (based on the top-up’s own sanction/renewal date), and the often-overlooked point that a top-up increases total exposure secured against the same property, with the same SARFAESI consequences on default as the base loan.

Bank Accounts

Loan Against Property

Loan Against Property (LAP) A Loan Against Property (LAP) lets you borrow against a residential or commercial property you already own — typically at 50–70% of its assessed value — for almost any purpose, at rates well below personal loans because the property secures the debt. This guide covers how LTV and valuation work, the floating-rate/EBLR structure (with the repo rate at 5.25% as of mid-2026), tenure norms, and documentation and fees. Two points get special attention: the new RBI (Pre-payment Charges on Loans) Directions, 2025, which ban foreclosure/prepayment charges on floating-rate LAP for individuals’ non-business purposes (loans sanctioned/renewed from 1 January 2026), and the tax treatment — LAP interest is deductible only if the funds are demonstrably used for business or for acquiring/improving another property, not for general personal use. We also cover what happens on default — the SARFAESI Act — and the difference between a fresh LAP and a top-up loan (Topic 24).

Bank Accounts

Maintaining Bank Accounts — The Hub & Spoke Strategy

Maintaining Bank Accounts — The Hub & Spoke Strategy A bank account is not just a wallet; it is your “Financial Identity”. Complexity is the enemy of wealth—managing 5 different “Salary Accounts” from old jobs is a recipe for fee leakage and fraud. Watch this video to learn the “Annual Bank Audit” checklist and simplify your financial life down to two accounts.

Book an Appointment Form